a = arcov(x,p)
returns the normalized autoregressive (AR) parameters corresponding to a model of order
p for the input array x, where
x is assumed to be the output of an AR system driven by white noise.
This method minimizes the forward prediction error in the least-squares sense.
Use a vector of polynomial coefficients to generate an AR(4) process by filtering 1024 samples of white noise. Use the covariance method to estimate the coefficients.
A = [1 -2.7607 3.8106 -2.6535 0.9238];
y = filter(1,A,0.2*randn(1024,1));
arcoeffs = arcov(y,4)
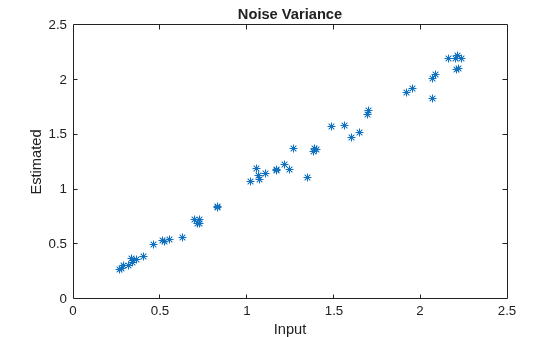
Generate 50 realizations of the process, changing each time the variance of the input noise. Compare the covariance-estimated variances to the actual values.
nrealiz = 50;
noisestdz = rand(1,nrealiz) + 0.5;
randnoise = randn(1024,nrealiz);
noisevar = zeros(1,nrealiz);
for k = 1:nrealiz
y = filter(1,A,noisestdz(k) * randnoise(:,k));
[arcoeffs,noisevar(k)] = arcov(y,4);
end
plot(noisestdz.^2,noisevar,"*")
title("Noise Variance")
xlabel("Input")
ylabel("Estimated")
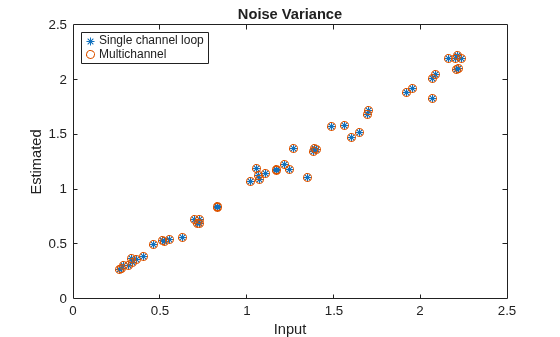
Repeat the procedure using the function's multichannel syntax.
Y = filter(1,A,noisestdz.*randnoise);
[coeffs,variances] = arcov(Y,4);
hold on
plot(noisestdz.^2,variances,"o")
hold off
legend("Single channel loop","Multichannel",Location="best")
Normalized autoregressive parameters, returned as a vector or matrix. If
x is a matrix, then each row of a
corresponds to a column of x. a has p + 1 columns and contains the AR system parameters, A(z), in descending powers of z.
White noise input variance, returned as a scalar or row vector. If x is a
matrix, then each element of e corresponds to a column of
x.
In an AR model of order p, the current output is a
linear combination of the past p outputs plus a white noise input. The
weights on the p past outputs minimize the mean squared prediction error
of the autoregression.
Let y(n) be a wide-sense stationary random process obtained by filtering white
noise of variance e with the system function A(z). If Py(ejω) is the power spectral density of y(n), then
Because the covariance method characterizes the input data using an all-pole model, the
correct choice of the model order, p, is important.
You clicked a link that corresponds to this MATLAB command:
Run the command by entering it in the MATLAB Command Window.
Web browsers do not support MATLAB commands.
Seleccione un país/idioma
Seleccione un país/idioma para obtener contenido traducido, si está disponible, y ver eventos y ofertas de productos y servicios locales. Según su ubicación geográfica, recomendamos que seleccione: .
También puede seleccionar uno de estos países/idiomas:
Cómo obtener el mejor rendimiento
Seleccione China (en idioma chino o inglés) para obtener el mejor rendimiento. Los sitios web de otros países no están optimizados para ser accedidos desde su ubicación geográfica.